We have all seen them – the social media adverts that promise Debt Review Termination and Clearance. These adverts are misleading and often just plain wrong. First, let us go over the differences between Debt Review Termination and Clearance.
What Is Debt Review Termination?
Debt Review Termination happens when you do not stick to the Debt Review payment plan that your Debt Counsellor has negotiated for you and default. Your creditors then terminate the Debt Review process. Your name will remain flagged as “under Debt Review” with the NCR and Credit Bureaus and you will NOT be able to get credit until you have settled your debt in full.
Debt Review Order Set Aside (Incorrectly referred to as Debt Review Termination)
We need to mention that you can have your Debt Review Order Set Aside (often incorrectly referred to as Debt Review Termination) but there is only ONE reason that will allow you this option – your financial circumstances have changed, for the better, and you are no longer considered to be over-indebted. You will need to go to court and have the Debt Review Court Order Set Aside and then continue paying your creditors as you did before.
IMPORTANT TO NOTE: Should the court agree and Set Aside your Debt Review Order, you will be responsible for the original amount you owe your creditors, NOT the reduced amount which your Debt Counsellor negotiated with them on your behalf.
What Is Debt Review Clearance?
This is when you can allow yourself a bit of a celebration. Debt Review Clearance happens when you have completed the Debt Review process and your Debt Counsellor supplies you with a Clearance Certificate 30 – 40 days later. Your Debt Counsellor will also send the Clearance Certificate to the NCR and the Credit Bureaus who will then remove the “under Debt Review” flag from your profile.
How Did I Become Over-Indebted?
There can be a lot of contributing factors that have gotten you to this place and 5 of them can include:
Poor money management
Not enough financial education
Not planning for when things go wrong
Over-spending on life events
Weddings
Funerals
Birthdays
Reduced income
Retrenchment
Retirement
Loss of one or more incomes in your home
Since 2007, when the NCA (National Credit Act) introduced Debt Review, also known as Debt Counselling, in South Africa, thousands of South Africans have successfully been able to clear their debt. As with any industry, there are pros and cons to Debt Review that you, the consumer, should and have to consider.
The overwhelming majority of consumers who have gone under Debt Review and completed the process successfully, swear by it. But, what happens when you are done with Debt Review? Here are the most common questions people ask when it comes to the termination and clearance when you have been under Debt Review.
Can I Terminate My Debt Review?
No, your creditors you owe money to can terminate your Debt Review if you do not stick to the agreement reached and that your Debt Counsellor negotiated on your behalf.
Can A Creditor Terminate Debt Review?
Yes, a creditor can terminate Debt Review under these circumstances:
Non-payment according to the payment plan that has been negotiated by your Debt Counsellor
This includes not paying the full instalment
The creditor does not accept the repayment amount set forward by your Debt Counsellor
Non-payment of the agreed-upon Payment Plan that your Debt Counsellor negotiated with your creditors on your behalf, is the biggest reason for creditors terminating Debt Review.
You need to remember that once you have missed a Debt Review payment, it gives your creditor/s the right to start legal proceedings against you – something that the Debt Review process protects you from.
My Financial Situation Has Changed. Can I Terminate Debt Review And Pay My Creditors Directly?
No, you can NOT terminate your Debt Review BUT you can have your Debt Review Order Set Aside.
If your circumstances have improved to the extent that you are able to make all your repayments that you owe to your creditors (according to the original credit agreement and NOT the reduced payment plan negotiated by your Debt Counsellor), you can apply to have your Debt Review Court Order Set Aside at the Magistrates Court. This is often, incorrectly, referred to as “Debt Review Termination and Clearance). The correct termination would be Debt Review Set Aside or Debt Review Rescinded.
This process involves you doing the following:
Apply to the court to have the Debt Review rescinded due to no longer being over-indebted
If the court rescinds the original Debt Review court order and you receive a court order that you are no longer over-indebted:
Credit Bureaus will be notified via the NCR system
You will have to continue paying the ORIGINAL payments – NOT the reduced payments negotiated by your Debt Counsellor
Creditors can once again take legal action against you if you miss any payments
What Else Can I Do If My Financial Situation Improves While I Am Under Debt Review?
If your financial situation has improved, speak to your Debt Counsellor and request a NEW payment plan that takes this into account, ensuring that you finish your Debt Review faster than originally planned. At Basson Debt Counsellors we are happy to renegotiate with your creditors and assist you in finishing the Debt Review process faster.
The benefits of doing this as opposed to rescinding your Debt Review are:
You do not lose the savings, from the reduced interest, that has already been negotiated with your creditors by your Debt Counsellor
As long as you are making your Debt Review payment on time, every month, creditors can NOT take legal action against you for any account in the Debt Review process.
Instead of asking “Can I stop my Debt Review and pay my creditors directly?” it should be – Why would you want to?
How Long Does Debt Review Stay On Your Name In South Africa?
As long OR as short a period of time as it takes you to complete the Debt Review process. This is obviously dependent on the amount of debt you are paying back. However, once you have met all your obligations and the debt has been settled, in full, the Debt Review flag is removed from your name. There is NO reference or mention of you having been under Debt Review on your Credit Record once you have been issued with a Clearance Certificate.
It is worth mentioning that once you have been issued with a Clearance Certificate, all adverse credit listings (ie. Slow payer etc and the Debt Review flag) will also be removed from your Credit Record.
What Happens When Debt Review Is Terminated?
If your Debt Review has been terminated because you have not made your monthly Debt Review Payment, the following will happen:
The Debt Review flag will remain on your name with Creditors and Credit Bureaus until you have settled all the debt that was placed under Debt Review and made an order of the court
Creditors can – and will – take legal action against all outstanding debt
You are automatically liable for the FULL outstanding debt, NOT the reduced amount that your Debt Counsellor negotiated on your behalf
What Is A Debt Review Clearance Certificate?
A Clearance Certificate is a notice to all your creditors that your debt, which was under Debt Review, has been settled in full.
Once you have successfully completed the Debt Review process, your Debt Counsellor will issue you with a Clearance Certificate. This Clearance Certificate will reflect all the debt that was under the Debt Review process that has been settled in full.
How Do I Get A Clearance Certificate For Debt Review?
Once you have successfully completed the Debt Review process, your Debt Counsellor will automatically issue you with a Clearance Certificate.
How Long Does It Take To Get My Clearance Certificate After Debt Review?
This is a process and does not happen overnight, but you should receive it on or about 21-days (working days) AFTER completion of the Debt Review process. However, as the saying goes “The road to hell is paved with good intentions” and to be fair to all parties concerned, give yourself 30-40 days before expecting your Clearance Certificate.
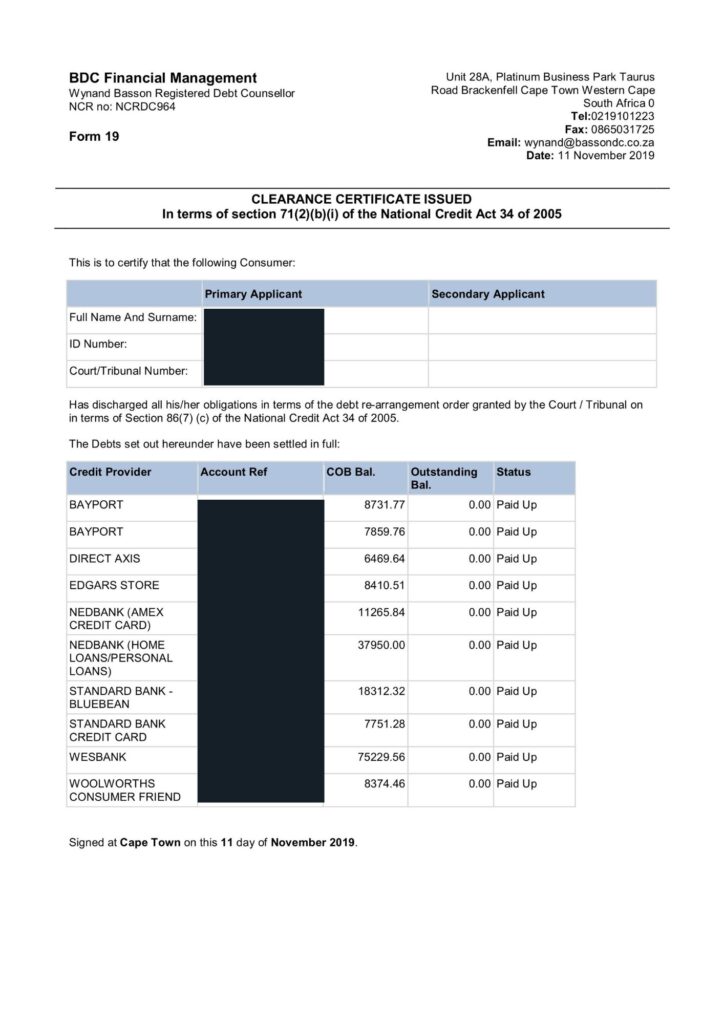
An actual Clearance Certificate that was issued once all debt was settled. The COB Balance = Full outstanding amount at the start of the Debt Review process.
It is worth remembering that the Debt Counsellor’s obligations end once you have received your Clearance Certificate. By this stage, they have notified all the Credit Bureaus that you have paid your debt in full and they have removed the ‘Under Debt Review’ flag from your name too.
Your Debt Counsellor has NO control over the time it takes the Credit Bureaus to update their system. Sadly, we have seen that the process to clear your credit record can, at times, take longer than expected. You can rest assured in knowing that at Basson Debt Counsellors, we will always do what we can to assist with this. However, our hands are tied when it comes to the time it takes to remove the flag from your name after we have supplied the Clearance Certificate to the NCR and Credit Bureaus. Rest assured – this does not usually take too long.
How Long After Receiving My Clearance Certificate Can I Apply For Credit?
Almost immediately, HOWEVER, you may want to sit back and take a breath. Firstly, you have worked extremely hard to get out of debt and we would recommend that you avoid getting back into debt right away.
The benefit of Debt Review is that once you have successfully completed the Debt Review process, your Credit Score would have been upgraded back to zero. Give yourself some time to build up from there because the last thing you want, is to have credit declined due to your Credit Score not being what it should be – and remember, being declined will also negatively affect your Credit Score. So, take a moment and do NOT take on too much credit to try and remedy your credit score because this may be counter-intuitive.
What Now?
We hope that this article has given you some clarity on the differences between Debt Review Termination and Clearance. If you have any further questions, call Basson Debt Counsellors or complete the call-back form below and we will happily assist.